Advertisement
Trust Bank vs DBS Multiplier, OCBC 360 and UOB One — Which Actually Pays More in 2026
Kept seeing "just use Multiplier/360/One" as the default answer whenever someone asks about savings accounts here, without Trust coming up at all, so wanted to put real numbers side by side rather than leave it as received wisdom.
The traditional three, briefly:
- DBS Multiplier is widely considered the best all-round pick for the least effort — no minimum salary requirement via GIRO credit, and a realistic effective rate around 2.50% p.a. for a simple salary-plus-spend combo on the first S$100,000.
- OCBC 360 has a higher theoretical ceiling if you stack all five categories (salary, save, spend, insure, invest), but most people who only manage salary plus save plus spend land closer to 1.95%–2.05% p.a. — it rewards discipline more than DBS Multiplier does, and slipping on the "grow your balance every month" condition even once costs you that category for the month.
- UOB One has a higher balance cap (up to roughly S$150,000) but has generally been considered less competitive after recent rate cuts, landing around 1.90% p.a. effective for salary-plus-spend.
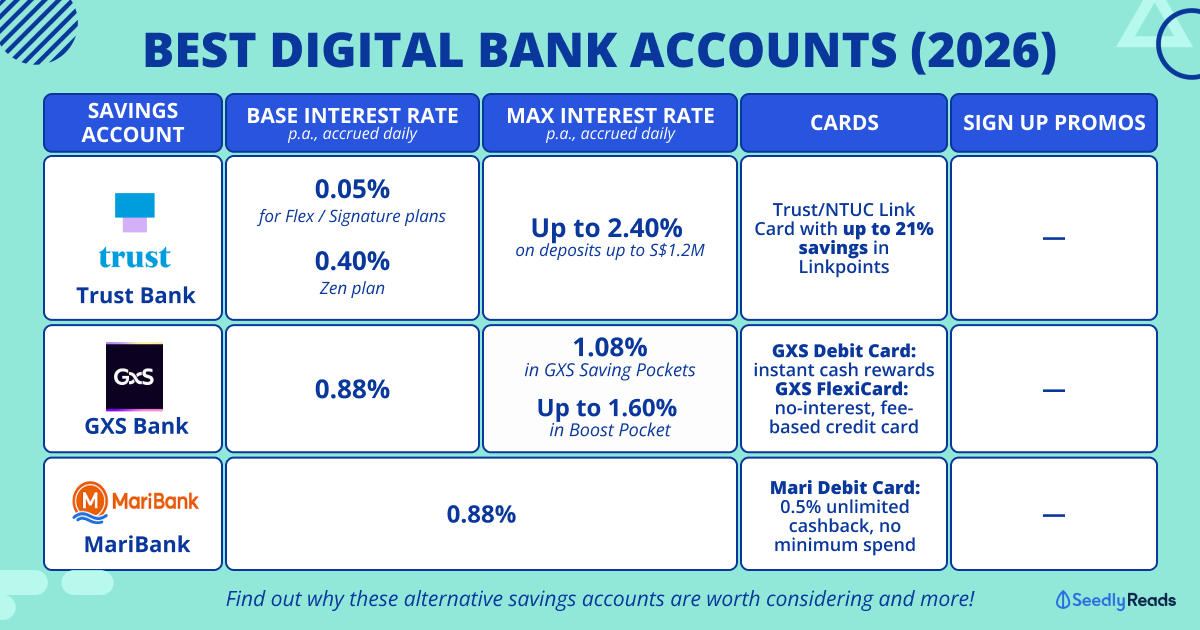
Where Trust fits into that: Trust's Signature/Flex plans advertise up to 2.40% p.a. (revised down from 2.50% earlier this year) on balances up to S$1.2 million — a far higher cap than any of the three traditional accounts — but getting near that headline rate means stacking multiple bonus "scoops" (salary crediting, card spend, balance growth, and so on) in the same month, not just one or two conditions. Trust's no-conditions Zen plan, for comparison, was reduced to 0.40% p.a. this past August — useful context if you were assuming the base rate alone gets you anywhere close to 2%.
My honest take on where each wins:
- If you want the highest realistic rate for the least ongoing effort on a salary-sized balance, DBS Multiplier is still hard to beat.
- If you're disciplined about growing your balance every month and already spend on an OCBC card, OCBC 360 can edge ahead.
- If you're holding a genuinely large balance well above S$150,000 and can realistically stack several Trust bonus conditions monthly, Trust's higher cap becomes relevant in a way none of the traditional three can match, since their bonus interest stops well below S$1.2 million.
- A lot of people I've seen doing this well just split — main salary account on DBS Multiplier or OCBC 360, and excess savings parked in Trust once cleared, rather than treating it as an either-or choice.
If you're opening Trust for this reason, the same referral mechanics apply as with any other Trust signup — a code has to go in before you start, and it unlocks a separate sure-win scratch card on top of whichever interest strategy you land on.
Steps and the current reward tiers are on this referral code page: https://dlcuration.com/trust-bank-referral-code...
Disclosure: referral link, small benefit to me if you sign up through it, no effect on your own reward.
Anyone actually running the "DBS Multiplier for salary, Trust for overflow" split — curious how the balance ends up divided in practice.
0
Discussion (0)
Learn how to style your text
Write your thoughts
Related Articles





Related Posts
Related Posts
Advertisement